
Auto Repair Financing Options: 2026 Guide
Table of Contents
How Auto Repair Financing Works
Car Repair Payment Plans at Service Centers
Buy Now Pay Later Services for Car Repair
Personal Loans and Credit Cards for Auto Repairs
Auto Repair Loans for Bad Credit
Comparison of Auto Repair Financing Options
Choosing the Right Auto Repair Financing Option
Conclusion
Last Updated: August 17, 2026
When your car needs a major repair, the sticker shock can be brutal. A transmission rebuild, engine work, or collision damage can easily exceed $3,000 or $5,000, money most people don't have in savings. Auto repair financing options let you spread the cost across manageable monthly payments instead of choosing between an empty bank account and a broken car.
But not all financing is created equal. Some options charge zero interest if you pay within six months. Others split costs into four interest-free installments. Still others offer traditional loans with fixed rates starting as low as 6% APR. The right choice depends on your credit score, the repair cost, and how quickly you can pay it back.
At Cruiser Auto Repair, we work with customers every day who face this decision. Many don't realize they have options beyond the shop's payment plan or a credit card. This guide walks you through every auto repair financing option available, how each works, what it costs, and who it's best for.
How Auto Repair Financing Works
Auto repair financing is straightforward: you borrow money to cover the repair cost, then repay it over time with interest or promotional terms. When you finance a repair, the lender pays the repair shop directly or reimburses you. You then owe the lender, not the shop.
Most auto repair financing falls into two categories: interest-bearing loans with fixed monthly payments, and promotional financing with a zero-interest window. Interest-bearing loans charge a percentage of the borrowed amount each month until paid off. Promotional financing gives you a grace period (typically 3 to 6 months) where no interest accrues if you pay the full balance by the deadline. Miss that deadline, and interest backdates to the original purchase date, sometimes at rates as high as 35% APR.

Understanding this difference is critical. A 0% APR offer sounds perfect until you realize you have only six months to pay. If your budget doesn't allow full repayment in that window, you'll face unexpected interest charges. Conversely, a loan with a fixed 12% APR and a 36-month repayment schedule costs more in total interest but gives you breathing room if cash flow tightens.
The repair shop typically doesn't set these terms. Cruiser Auto Repair partners with financing providers to offer customers multiple options at the point of service, so you can compare rates and terms before committing.
Car Repair Payment Plans at Service Centers
Many repair shops offer in-house payment plans managed through third-party financing companies. You approve the repair and sign an agreement to pay in installments over 6 to 12 months. The shop receives payment from the financing partner immediately, and you pay the financing company monthly.
The advantage is convenience. You're already at the service center, and the financing option is right there with no separate application process. Many shops partner with established lenders, so terms are standardized and transparent.
The drawback is that shop payment plans often don't offer the best rates compared to other options. A shop might offer 0% APR for 12 months, but a credit card or buy-now-pay-later service might offer better terms. It's worth asking what the shop offers, but don't assume it's your only choice.
Cruiser Auto Repair works directly with financing providers to ensure customers have multiple options at point of service, so you're not locked into one plan.
Buy Now Pay Later Services for Car Repair
Buy-now-pay-later (BNPL) services have expanded into auto repair, letting you split the repair cost into smaller payments, often with zero interest if you pay on time.
The most common BNPL structure is four interest-free payments spread over six weeks. You pay 25% upfront, then three more equal payments every two weeks. If you miss a payment, late fees apply, but as long as you stay current, there's no interest.
Services like Affirm, Klarna, and Afterpay operate this way. They handle approval (usually with a soft credit check that doesn't hurt your credit score), pay the repair shop directly, and collect from you over time. The application takes minutes, and you often get an instant decision.
The strength of BNPL is flexibility and transparency. You know exactly what you'll pay, there are no hidden fees if you stay on schedule, and the soft credit check means people with lower credit scores can still qualify. Many BNPL services also offer longer payment plans (6 to 12 months) for larger repairs, sometimes with 0% interest for qualified customers.
The weakness is availability. Not every repair shop partners with every BNPL service. Additionally, BNPL services work best for repairs under $2,000. For larger jobs, payment terms become less attractive.
Personal Loans and Credit Cards for Auto Repairs
Personal loans and credit cards are the traditional backbone of auto repair financing. A personal loan is an unsecured loan from a bank or online lender, typically ranging from $1,000 to $100,000, with fixed interest rates and fixed repayment terms (3 to 7 years).
The advantage is predictability. You know your monthly payment, interest rate, and payoff date from day one. If you have good credit, rates can be competitive, sometimes as low as 7% APR. You can borrow enough to cover the repair and have cash left over for other needs.
The disadvantage is the application process. Personal loans require a hard credit inquiry, which temporarily lowers your credit score. Approval can take several days. If your credit is below 650, you may not qualify for the best rates.
Credit cards designed for automotive expenses, like the Synchrony Car Care card, offer promotional financing (often 6 months 0% APR on purchases over $199) plus acceptance at over 1 million auto merchants nationwide. No annual fee, and if you pay the balance during the promotional window, you owe nothing extra.
The catch is the standard APR if you don't pay in full during the promotion. Interest rates on automotive credit cards typically range from 25% to 35% APR. If you can't pay off the balance in six months, you'll face steep interest charges.

PayPal Credit offers 6 months 0% APR on purchases of $149 or more at online automotive retailers and some shops that accept PayPal. The same caveat applies: miss the deadline, and interest backdates to the original purchase.
Auto Repair Loans for Bad Credit
If your credit score is below 650, traditional personal loans become harder to secure. Specialized bad-credit auto repair lenders like Oportun and Upstart focus on borrowers with limited or damaged credit, using alternative underwriting methods such as education and employment history.
The advantage is accessibility. You can qualify for a loan even with a lower credit score or thin credit file. Approval is often fast (sometimes same-day), and funds arrive quickly. Some lenders, like Oportun, report on-time payments to credit bureaus to help you build credit.
The disadvantage is cost. Interest rates for bad-credit loans typically range from 20% to 36% APR. Origination fees (charged upfront) can be 1% to 15% of the loan amount. A $3,000 repair financed at 30% APR with a 10% origination fee costs significantly more than the same repair through a traditional lender.
LightStream, owned by SoFi, offers auto repair loans starting at 7.64% APR for those with good to excellent credit, but requires a minimum loan amount of $5,000. Oportun and Upstart have lower minimums and more flexible credit requirements.
The key with bad-credit financing is to compare total cost, not just APR. A 24% APR over 36 months might cost less in total interest than a 30% APR over 24 months, depending on the principal amount.
Comparison of Auto Repair Financing Options
Here's how the major auto repair financing options stack up:
Option | Best For | Interest Rate | Approval Time | Key Benefit |
Shop Payment Plan | Convenience at point of service | Varies (often 0% for 6-12 months) | Instant | No separate application |
Affirm (BNPL) | Repairs under $2,000 | 0-36% APR | Minutes | Transparent, no hidden fees |
Klarna (BNPL) | Quick payment splits | 0% for 4 payments, then varies | Minutes | Interest-free short-term option |
Afterpay (BNPL) | Smaller repairs | 0% for 4 payments | Minutes | Simple structure, up to $2,000 |
Synchrony Car Care Card | Repeat auto expenses | 0% for 6 months (then 25-35% APR) | Hours to 1 day | Accepted at 1M+ merchants |
CFNA Cards (Firestone, etc.) | Shop-specific financing | 0% for 6 months (then 28-30% APR) | Hours to 1 day | Tied to specific retailers |
PayPal Credit | Online auto parts/services | 0% for 6 months (then 29.89% APR) | Hours | Works for online purchases |
LightStream Personal Loan | Large repairs, good credit | 7.64-15.24% APR | Same-day to 1 day | Lowest rates, no fees |
Upstart Personal Loan | Fair credit, quick funding | 6.2-35.99% APR | 1-2 business days | Alternative underwriting |
Oportun Personal Loan | Bad credit, credit building | Varies (contact for rates) | 1-2 business days | Reports to credit bureaus |
No single option is best for everyone. Your choice depends on the repair cost, your credit score, how quickly you need the money, and whether you can commit to paying within a promotional window.
Pro Tip Before committing to any financing option, ask the repair shop what they offer in-house. Cruiser Auto Repair can discuss multiple options with you upfront so you're not surprised by terms or rates. Many shops have partnerships that aren't advertised online.
Choosing the Right Auto Repair Financing Option
Selecting the right financing option requires answering a few questions about your situation.
What's your credit score? If it's above 700, personal loans and credit cards offer the best rates. If it's between 650 and 700, you have decent options but may face higher APRs. Below 650, BNPL services or specialized bad-credit lenders are more realistic.
How much is the repair? For repairs under $1,000, BNPL services (Klarna, Afterpay) are efficient and cost-effective. For repairs between $1,000 and $3,000, shop payment plans or credit cards with promotional financing make sense. For repairs over $3,000, a personal loan with a fixed rate often beats promotional financing because you have more time to pay.
How quickly can you pay? If you can pay within 3 to 6 months, promotional financing (0% APR) is your best bet. If you need 12+ months to pay, a fixed-rate personal loan is safer because you won't face surprise interest charges if you miss the promotional deadline.
Can you handle a hard credit inquiry? Personal loans require a hard credit check, which temporarily lowers your score by 5 to 10 points. If you're about to apply for a mortgage or car loan, this timing matters. BNPL and some credit cards use soft pulls that don't affect your score.
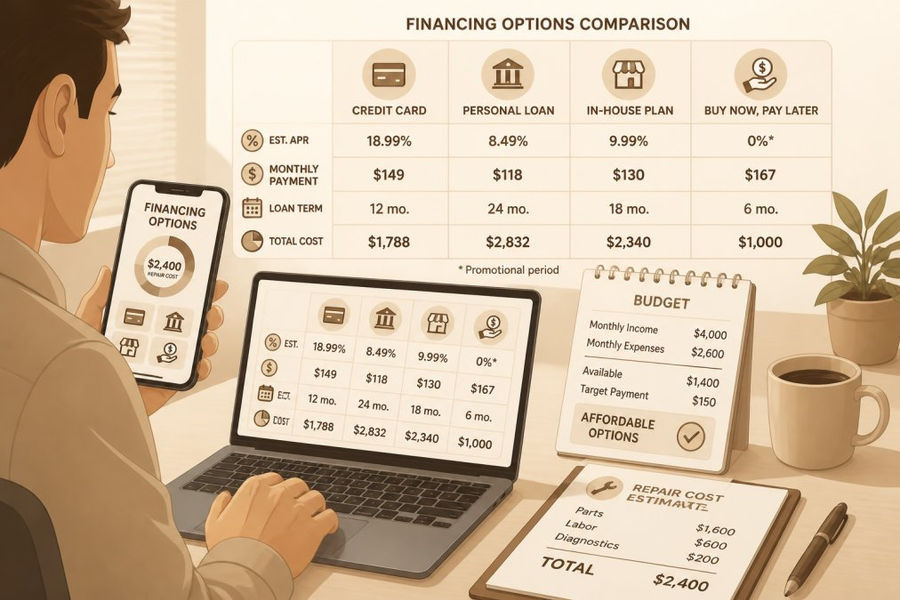
Do you have a relationship with the shop? If you've worked with Cruiser Auto Repair or another trusted shop before, their in-house financing options are worth considering.
Here's a decision framework:
Under $1,000 + can pay in 4-6 weeks: Use Klarna or Afterpay
$1,000-$3,000 + credit score 700+ + can pay in 6 months: Use a promotional credit card (Synchrony, CFNA, PayPal Credit)
$1,000-$3,000 + credit score below 700: Use Affirm or Klarna
Over $3,000 + credit score 700+ + need 12+ months: Use a personal loan from LightStream or SoFi
Over $3,000 + credit score below 700: Use Upstart or Oportun
Any amount + want simplicity + trust the shop: Use the shop's in-house payment plan
The worst mistake is choosing financing based solely on the lowest monthly payment. A $3,000 repair financed at 35% APR over 36 months costs about $1,700 in interest. The same repair at 10% APR over 36 months costs about $500 in interest. Always calculate the total interest cost, not just the monthly payment.
Watch Out Watch for deferred-interest traps. A "0% APR for 6 months" offer sounds great until you miss the deadline by one payment. Interest then backdates to the original purchase date at the card's standard APR (often 25-35%), turning a $3,000 repair into a $3,500+ debt. Set a phone reminder for the final payment date.
Choosing the right auto repair financing option is about matching the terms to your financial situation. You don't need to accept the first option the shop presents. Compare rates, understand the total cost (not just the monthly payment), and choose the option that lets you afford the repair without overextending yourself.
When you bring your car to Cruiser Auto Repair for service, our team can discuss your financing options upfront and help you understand the true cost of each choice. We handle extended warranty repairs directly with providers, which means we can often expedite approval and get your car back on the road faster. Schedule your appointment today and let us help you find the financing solution that works for your budget.
Frequently Asked Questions
Is there a way to finance auto repairs?
Yes, multiple auto repair financing options exist. You can use personal loans from lenders like LightStream or Upstart, credit cards including the Synchrony Car Care Card, buy now pay later services like Affirm and Klarna, or in-house payment plans through repair shops. Each option has different interest rates, terms, and eligibility requirements. The best choice depends on your credit score, repair cost, and ability to repay.
Does bad credit affect my ability to get auto repair financing?
Bad credit can limit your options and result in higher interest rates, but it doesn't eliminate them. Lenders like Upstart and Oportun consider factors beyond credit scores, including employment and education history. Buy now pay later services often use soft credit checks that don't impact your score. In-house payment plans through repair shops may also be available regardless of credit history. Shop around to find lenders willing to work with your credit situation.
What are the interest rates for auto repair loans?
Interest rates vary widely depending on the financing method and your creditworthiness. Personal loans range from 6.2% to 35.99% APR. Credit cards typically charge 28.8% to 39.99% APR. Buy now pay later services offer 0% APR for shorter terms or promotional periods, with rates up to 36% for longer financing. Some options feature 0% APR if you pay within a specified period (typically 6 months). Always review the terms before committing.
Can you make a payment plan for car repairs?
Yes. Many repair shops offer in-house payment plans that allow you to spread costs over several months with fixed payments. Additionally, third-party financing through services like Affirm, Klarna, and Afterpay enables payment plans directly at participating repair shops. These options provide flexibility without requiring a separate loan application, though terms and interest rates vary. Ask your repair shop which financing methods they accept.
What is the $3,000 rule for cars?
The $3,000 rule is an informal guideline suggesting that if a major repair exceeds $3,000 or more, it may be worth considering whether to repair or replace the vehicle. For repairs approaching or exceeding this threshold, financing becomes more attractive since the cost is substantial. However, the decision depends on your vehicle's age, overall condition, and remaining useful life. Financing can make the repair manageable by spreading payments over time rather than paying a large sum upfront.
SCHEDULE YOUR APPOINTMENT
This article was written using GrandRanker


Comments